Quick Summary
An Enrolled Agent, or EA, is a federally licensed tax professional authorized by the IRS to help taxpayers with federal tax matters, including preparing returns and representing them before the IRS when properly authorized. At Purposeful Money, I hold both CFP® and Enrolled Agent credentials, which helps me connect retirement planning decisions with tax strategy and federal tax preparation in one coordinated, plain-English conversation.
If you are approaching retirement or already retired in Southwest Florida, it is understandable to assume that every financial advisor handles taxes. In reality, many advisors provide investment guidance or retirement projections but do not prepare tax returns or represent clients before the IRS. That distinction matters when choices about withdrawals, Social Security, Medicare premiums, charitable giving, and required minimum distributions can affect one another.
What an Enrolled Agent Does
An Enrolled Agent is a tax professional licensed at the federal level by the IRS. Unlike a credential limited to one state, the EA designation is centered specifically on federal taxation. EAs may prepare federal tax returns and, with appropriate authorization from a taxpayer, represent taxpayers before the IRS in audits, collections, and appeals.
To become an EA, an individual generally qualifies in one of two ways. The most common route is passing the IRS Special Enrollment Examination, a rigorous three-part exam covering individual taxation, business taxation, and representation, practices, and procedures. A person also may qualify through certain former IRS experience that demonstrates substantial technical tax knowledge.
Becoming an EA is not a one-time accomplishment. Enrolled Agents must meet ongoing continuing-education requirements and follow ethical standards established by the IRS. Tax rules change, and maintaining the credential requires continued attention to those changes.
Why Federal Tax Expertise Matters in Retirement
Retirement is not simply the point when a paycheck stops. It is a transition into a new set of financial decisions, often involving multiple income sources and a different tax picture. The timing and source of income can influence your federal tax bill today and your options in future years.
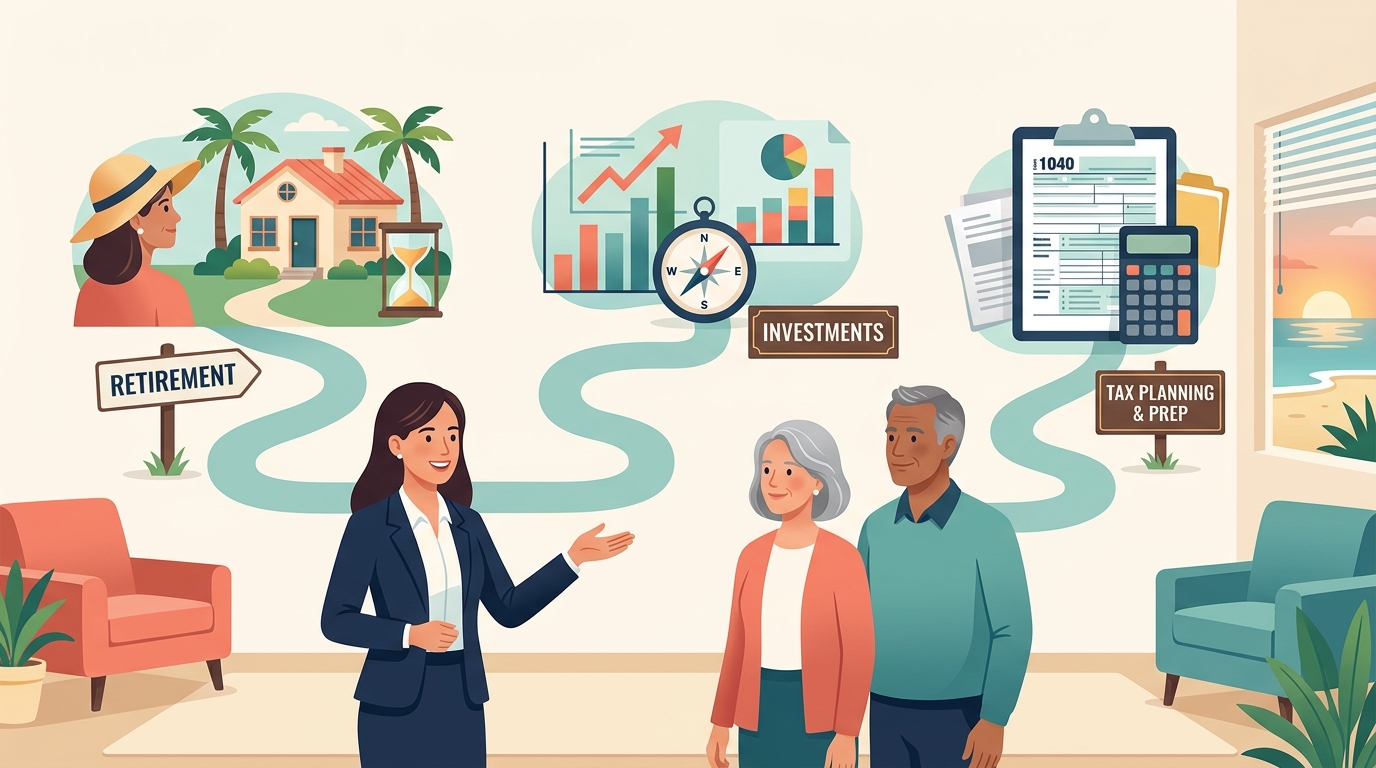
For example, a retirement income plan may involve withdrawals from traditional IRAs, Roth accounts, taxable investments, pensions, and Social Security. A decision that appears reasonable in isolation can have broader consequences. It may affect your marginal tax bracket, the taxation of Social Security benefits, Medicare IRMAA surcharges, or the size of future required minimum distributions.
This is why tax planning for retirement should be connected to the larger plan rather than treated as a once-a-year filing task. At Purposeful Money, I look at how tax preparation and planning can fit alongside investment management aligned with your retirement goals, Social Security claiming decisions, Medicare guidance, estate planning coordination, and the life you want your money to support.
How an EA Differs From a CPA
Both Enrolled Agents and Certified Public Accountants can be highly qualified tax professionals, and neither designation is universally “better.” They are different credentials with different scopes.
An EA is federally licensed and focused on taxation. The designation reflects specialized knowledge of federal tax law and federal tax representation. When properly authorized, EAs have unlimited representation rights before the IRS, meaning they can represent any taxpayer on any federal tax matter within their authority.
A CPA is licensed by a state board of accountancy. CPA licensure covers a wider accounting field that can include taxation, accounting, auditing, financial reporting, and business advisory work. CPAs who meet applicable requirements also can have unlimited representation rights before the IRS when properly authorized.
The right fit depends on the work you need done and the professional’s experience. Some CPAs focus deeply on tax planning; others focus on audit, accounting, or business services. Some EAs specialize in individual and retirement-related tax matters; others work with businesses or tax controversy. What matters most is understanding the professional’s actual services, qualifications, and approach.
Why Not Every Financial Advisor Handles Taxes
“Financial advisor” is a broad term. Advisors may focus on investments, insurance, retirement-income projections, portfolio management, or financial planning. Many do valuable work, but many do not prepare tax returns and do not represent clients before the IRS.
That does not make their guidance incomplete by definition. It does mean you should ask clear questions: Does your advisor coordinate with your tax professional? Do they discuss the tax implications of retirement withdrawals? Can they help you evaluate the tradeoffs behind a Roth conversion, charitable gift, or required minimum distribution? Who will prepare the return and be available if the IRS has a question?
For retirees and pre-retirees, especially women navigating a career change, divorce, widowhood, or another life transition, these questions can bring welcome clarity. You deserve a trusted financial partner who explains the moving pieces without judgment or jargon.
How My CFP® and EA Credentials Work Together
As a CFP® professional, I am trained to take a comprehensive view of your financial life: retirement readiness, cash flow, investments, risk management, insurance, Social Security, Medicare, and legacy goals. As an Enrolled Agent, I also bring federal tax expertise to that conversation.
At Purposeful Money, that combination helps close the gap between financial planning and tax decisions. We can consider how a retirement withdrawal strategy may interact with projected taxable income, how investment decisions may create tax consequences, and how preparation of a federal return can inform planning for the next year. It is not about chasing a tax outcome at the expense of your larger goals. It is about making informed tradeoffs with the full picture in view.
My approach is relationship-first and life-centered. Your plan should support more than a spreadsheet. Through my Season of You™ and Long Run Retirement Method, I help clients explore what retirement can look like financially and personally—whether that means more time with family, meaningful travel, charitable giving, a second act, or simply greater confidence in everyday decisions.
Retirement Tax Questions Worth Raising Early
You do not need to know every rule before speaking with a professional. Starting with the questions that are already on your mind is enough. During retirement transition planning, useful topics may include:
- How will IRA withdrawals, pensions, and investment income affect my projected federal taxable income?
- When should I begin Social Security, and how could that choice fit with my broader retirement income plan?
- Could a future required minimum distribution push me into a higher tax bracket?
- How might income affect Medicare IRMAA surcharges?
- Should I coordinate charitable giving, Roth conversions, or other tax-sensitive decisions before year-end?
- Who will prepare my federal return and help address an IRS notice if one arrives?
There is no universal answer to these questions. The appropriate path depends on your income sources, account types, goals, family circumstances, and the tax laws in effect at the time. Still, asking early gives you more room to evaluate choices thoughtfully rather than reacting under a deadline.
A Coordinated, Plain-English Approach
At Purposeful Money in Naples, I work with retirees and pre-retirees in Southwest Florida and virtually with clients nationwide who want retirement guidance to feel more connected. My role is to help you understand the decisions in front of you, identify where tax considerations may matter, and keep your plan aligned with your values and long-term goals.
You can learn more about Tax Planning & Preparation
and how it may fit into a holistic retirement plan. You can also visit About Erin O'Brien
to learn more about my background, credentials, and approach.
If you are looking for a financial advisor in Southwest Florida who can help bring retirement planning, investment decisions, and federal tax preparation into a more coordinated conversation, I would be glad to connect. Schedule Your Learn More Call at 800-520-9793
or https://www.purposefulmoney.com/contact.
Educational information only; this article is not individualized tax, legal, investment, or financial advice. Tax laws and IRS procedures can change, and your decisions should be evaluated based on your personal circumstances.
Read More Articles
What Is an Enrolled Agent — and Why Should Your Retirement Advisor Be One?
The Hidden Tax Traps in Retirement — and How to Avoid Them
Read more
The Long Run Retirement Method: A Holistic Approach for Women Navigating Retirement in Southwest Florida
Read more
What the September Fed Meeting Means for Retirement Plans
Why a One-Time Financial Plan Fails Retirees — and What Ongoing Planning Really Requires
What Comprehensive Retirement Planning Really Means for Women in Southwest Florida
Inheritance Planning and Tax-Smart Financial Decisions
Why Fee‑Only Financial Advice Matters for Women Approaching Retirement
How to Know If Your Financial Advisor Is Truly a Fiduciary (A Guide for Women Retiring in Naples & Southwest Florida)
What it means to work with a fee-only fiduciary financial advisor — and why that distinction matters deeply for women approaching retirement
When Claiming Social Security Early Can Actually Help Women Retiring
Read more
5 Common Retirement Planning Mistakes (and How to Avoid Them)
Understanding Accelerated Death Benefit Riders
Maximize Your IRA and HSA Contributions Before Tax Day Arrives
Understanding Long-Term Care Riders in Your Life Insurance Plan
Retirement Planning Strategies for Adults Managing Student Loans
A Fresh Start for Your Finances: Your January Guide to Building Financial Wellness
December 2025 Market Recap: A Year’s Final Turn
Turkey Talk: 5 Financial Questions Advisors Often Hear

What's in my wallet?
Exploring Major Types of Investment Vehicles

5 Key Economic Terms Simplified for Your Financial Insight
Back-to-School Money Moves: A Financial Game Plan
Check In with Your 2025 Financial Plans Mid-Year
A Grain of SALT in the Big Beautiful Bill
Big Beautiful Bill- What's in it for Who?

Exploring Life Insurance: A Key to Financial Literacy
Navigating Risk Tolerance for Investment Success
Read more
Simplify Annuity Choices for Your Financial Future

Take Charge of Financial Wellness Month 2025
Understanding Adjustable-Rate Mortgages in a Changing Market
Exploring Charitable Giving Options: Maximize Impact and Benefits
Read more